A story on rising pet ownership in China jarred my pedant-bone when it quoted the claim that pets are “an asset that has no economic value”.
The Rational Standard recently carried an article by Viv Vermaak, an associate of the Free Market Foundation and regular Daily Friend writer, about what rising ownership of cats and dogs – as pets – tells us about Chinese society.
Mao’s regime condemned pet-keeping as bourgeois, and dog ownership was banned in most Chinese cities until 1993 (albeit because of a rabies outbreak). Vermaak argues that the rise of pet ownership signals a degree of bourgeois aspiration more consistent with a free-market economy than with China’s official state ideology of communism.
It is a good argument. It has been clear for a long time that China, for all its one-party authoritarianism, relies strongly on capitalist markets for its rapid growth, rising prosperity, and global competitiveness. Vermaak’s article adds a new dimension to the story, by considering what we can learn from the growing popularity of keeping cats and dogs. It is well worth reading, if only for the name “Miaow Tse-Tung”.
I want to quibble, however. (That’s what makes me such fun at parties, and why it’s probably better I live far from the madding crowd these days.)
“No economic value”
Vermaak quotes Frans Cronje, former CEO of the Institute of Race Relations (which publishes the Daily Friend) and co-founder of The Common Sense, as saying: “Pet ownership breeds individualism, individualism that creates ownership around an asset that has no economic value.”
I’m sure he just meant pets cost money without making any, but given his phrasing, I would venture to dispute that dogs and cats have “no economic value”.
I don’t mean that in some cases they can be bred for money or can be working animals that perform a job. I mean a pet that exists for no other purpose than having its tummy scratched and eating yummy treats is an asset that has economic value.
It might sound like I’m just being argumentative for the sake of pedantry (and I’ll admit, I enjoy a bit of fine pedantry of an evening), but it goes to the heart of how free-market thinkers conceive of economic behaviour in our society.
The short version is that anything a person values has, by that fact alone, economic value.
Economic value is not an objective characteristic that can be attributed to something only when it produces revenue, or can be sold for a known price, or performs a useful function (for some value of “useful”). Economic value is entirely subjective.
If that sounds like the subjective theory of value, which stands opposed to the Marxist labour theory of value, then that is no coincidence.
Subjective value
A key insight for anyone devising economic policy is that no external agent (like a government bureaucrat, or even “the market”) can determine what value a product or service has to a person – until the person reveals their preference by making a decision to buy or sell it (or to refuse to buy or sell it). Not even the person themselves can put an authoritative value on something until they have to bite the bullet and make the decision.
Every human action – every act of purposeful behaviour – is chosen from among many potential alternatives. Every choice weighs up a potentially infinite set of wants and needs against the scarce means available to achieve those ends.
That is the very definition of economics. Nothing says the means have to be financially quantifiable. Nothing says the wants and needs need to have monetary value.
Any choice involving limited resources (such as time, labour, money, space, connections, or knowledge) to pursue any want or need (such as sustenance, shelter, pleasure, healthcare, safety, long-term financial security, short-term profit, emotional satisfaction, joy, love, esteem, or Mazlow’s vaunted “self-actualisation”) is an economic decision.
Money can’t buy you love
Think you can’t put a price on love, or happiness? Not in monetary terms, perhaps, but their value is implicitly revealed by what someone is prepared to give up to attain (or retain) them.
The same goes for choices that seem entirely social or moral. Those choices, too, always come at a cost.
Security often comes at the price of freedom. The choice to intervene to prevent harm to another, or to correct a perceived injustice, could come at the cost of personal safety. The desire to share resources in a community does not make those resources free. Waging war on an enemy often requires tolerating a degree of unintended harm to innocent civilians. Obtaining medicine for someone who is dying or food for someone who is starving might come at the cost of respecting the property rights of its producer. Supporting companies that do not pollute or exploit their workers comes at the cost of higher prices (and sometimes the unemployment of the “exploited” workers). Improving corporate efficiency can be a trade-off against better employee working conditions.
All of these choices involve subjective valuations of what is important to an individual, and how these valuations are made can differ wildly from one person to the next.
Not my idea
None of this is my original idea. Carl Menger, who founded the Austrian school of economics with his Principles of Economics in 1871, argued that value is not a property of goods at all.
It is the importance we attach to satisfying our own needs, which we then carry over to the goods that satisfy them. That is why the same good can be worth a great deal to one person, little to another, and nothing at all to a third.
In 1932, Lionel Robbins of the London School of Economics gave the profession the definition it still teaches. Economics, he wrote, studies human behaviour as “a relationship between ends and scarce means which have alternative uses”. That definition says nothing about money, markets or commerce. Robbins also held that economics is neutral between ends. An end is an end, whether it is a factory, a Ford or a fox terrier.
Robbins drew the boundaries of economics widely. Ludwig von Mises erased them altogether. In Human Action (1949), he argued that economics was merely the best-developed branch of a general science of human action, because “choosing determines all human decisions”. Material and ideal ends, the noble and the base, all compete on a single scale of preference, and every choice picks one and sets the others aside.
His protégé, Friedrich Hayek, wrote in The Counter-Revolution of Science (1952): “It is probably no exaggeration to say that every important advance in economic theory during the last hundred years was a further step in the consistent application of subjectivism.”
Gary Becker of the University of Chicago won the Nobel prize in 1992 for taking this seriously. He applied economic reasoning to discrimination, crime, education and the family. In his Nobel lecture, entitled The Economic Way of Looking at Life, he stressed that this does not assume people are greedy. It assumes only that people pursue their own welfare as they conceive it, “whether they be selfish, altruistic, loyal, spiteful, or masochistic”.
None of them would have accepted that a thing nobody can sell has no economic value.
Pets as assets
When someone chooses to spend money on a pet, that reveals that they value having a pet more than they value the money it costs to keep that pet, and the time it takes to look after it.
That is an economic decision. Not everyone will agree. If you hate dogs, or you’re allergic to cats, the subjective value you attribute to these animals will be very different.
If you do love pets, however, and you derive emotional support or satisfaction from your relationship with them, then pets are an asset to you. They produce something you value more than what it costs to keep them; therefore, they are economically valuable assets.
If I choose to spend a day working instead of spending it with my family, that is an economic decision. I’m willing to trade something that I value for something that I feel I need more.
Conversely, if I spend an afternoon taking a nap, that is also an economic decision. It reveals that I value a snooze more highly than anything else on which I might spend my limited time. The snooze has economic value because I attribute subjective value to it, independently of anyone else.
I can’t sell that snooze. Nobody will buy it from me. It hasn’t made me any money. Yet choosing it over other ways to spend my time is an economic decision, based on the value I subjectively attach to that snooze.
The souped-up car
For some people, a car is a utility tool that gets them from A to B without consuming too much fuel or causing them too much grief. For other people, a car is a pleasure, on which they happily spend money and time, and whose value to them is much higher than it is to anyone else.
When you see someone drive around with lowered suspension and a Temu bodykit, that is not a productive investment of their limited resources in the sense that it will ultimately make them money. It patently won’t.
It is productive in the sense that it satisfies some subjective wants and needs. They are not wants and needs that I can understand. I don’t value such things, and I cannot comprehend why some people do. But that is the point of value being subjective. Its value isn’t for me to decide, and in principle, I cannot decide its value.
If nobody would pay more for such a car than they’d pay for the base model, that is not a claim that the modifications have no economic value. That is merely a disagreement on price. It says only that the modifications have no economic value to the would-be buyer. They plainly do have economic value to the owner – otherwise the owner wouldn’t have paid for them.
Whether it’s a vintage Rolls-Royce that appreciates in value, or a classic Jaguar that breaks faster than it can be fixed (an economic asset with which I have some personal experience), a souped-up Golf, or the proverbial little old lady’s shopping car, each can only be valued subjectively.
Market value
If a market value can be established, then that merely says that two or more people can agree on a monetary value for the thing. If no market value can be established, that does not mean that the thing has no economic value to its owner.
There is no such thing as an objective value. The closest we can come to it is a putative market value, but market values are so inconsistent precisely because nothing has intrinsic value. You can’t even know the exact market value of something until you actually sell it.
When a municipality values your house for the purpose of rates and taxes, is that its market value? They’d like to think so. Yet its value is quite unknown until you actually sell it and can get at least one other person to agree on its value.
For some people, the value of their house is infinite: they won’t sell for any price. For others, the value of the same house might be quite low: they don’t want to live there, and want to be rid of it. Same house, two entirely different values.
All value is subjective, and all prices are determined by the interaction between the subjective valuations of two or more people. The only thing that has no value is a thing that nobody wants or needs. That list is probably quite long, but it does not include pets.
Labour theory of value
This is also why the labour theory of value is so flawed. If you agree to work for someone, the subjective value of your wage is revealed to be higher than the subjective value of the time and effort it takes to earn that wage. If it weren’t, you wouldn’t have taken the job.
Conversely, your employer values your labour more than the wage it pays you. If they didn’t, they wouldn’t have hired you.
Your labour has no value in the absence of someone who subjectively values it, or what it produces. You can dig holes and fill them in again all day long, and you will not be creating value (other than for yourself, if you happen to like that sort of thing).
Marx saw this objection coming. In the first chapter of Capital, he conceded that a useless thing has no value: “If the thing is useless, so is the labour contained in it.”
But that concession gives the game away. If labour counts only when someone wants what it produces, then it is the wanting, not the labour, that confers value. Then value is subjective.
The only reason labour might have a higher subjective value to your employer than to you or someone else is that they have the means to combine that labour with other resources – capital, raw materials, other people’s labour, knowledge, legal authorisations, connections, market access – to make it more valuable to them and their customers than its value to you.
If you spend your day making smartphones, despite already having one, what makes that work valuable? Only the fact that it satisfies the subjective wants and needs of customers. As soon as demand is satisfied, or shifts elsewhere, it would be pointless for you to carry on making unwanted smartphones. You’re not creating value by virtue of the labour you invest. You create value by virtue of the fact that someone else wants what you produce.
That is why profit is not “unearned”. It is not “surplus value”, extracted from workers by the “capitalist class”. It is exactly the value of the entrepreneur’s ability to orchestrate scarce resources, including labour, to produce something that customers subjectively value more than the price they pay for it.
Worth every yuan
Which brings us back to China’s cats and dogs.
According to data reported by Beijing’s State Council Information Office, China’s cities were home to 126 million pet dogs and cats in 2025, and their owners spent 312.6 billion yuan – about $45 billion or R745 billion – on them.
On Cronje’s reading, that is $45 billion spent on assets of no economic value.
By the subjective theory of value, however, it is $45 billion worth of evidence of value.
Every yuan represents something an owner chose to give up – a meal out, a new phone, a bit more in savings – in exchange for a purring furball or a wagging tail. Millions of households make that trade every day.
Vermaak calls this “economic development at its most wonderfully irrational”. It is nothing of the sort. It is perfectly rational for people who value companionship more than they value the money it costs.
Cronje, who is no Marxist, has in fact stumbled onto Marx’s position. In Marx’s scheme, a pet that nobody intends to sell is not a commodity, and a stray that nobody laboured to produce has no value at all. (Don’t try to read this. Marx is incomprehensible: “As values, all commodities are only definite masses of congealed labour time.”)
The labour theory of value has no column in its ledger for love.
It cannot explain the stray, either. A pedigree puppy may cost thousands of yuan. A kitten rescued from a gutter costs nothing and embodies no labour at all, yet its owner may love it every bit as much. Menger put it neatly: “what one person abandons is often picked up by another”.
Nor did labour create the value of China’s pet economy. The vets, groomers, pet-food makers and the staff of the pet transport service on China’s high-speed trains did not make pets valuable.
Pets were valuable to their owners first, and the labour followed.
An emerging industry
Richard Whately made the point about pearls in his Oxford lectures of 1831: “It is not that pearls fetch a high price because men have dived for them; but on the contrary, men dive for them because they fetch a high price.”
And they fetch that price only because someone made a subjective value judgement that they’d prefer to own that pearl instead of its price in money.
Even the Communist Party has noticed. The mayor of Anshan, a former steel town, promised in 2025 to vigorously expand its pet economy. A regime whose Red Guards once killed pets as a sign of bourgeois living now courts an industry that sells them dyed hair and birthday cakes.
Not bad for an asset with no economic value.
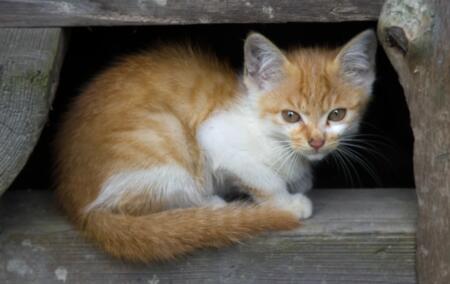
[Image: A kitten photographed in Dimen Village in Guizhou, China. (Photo: Marie Anna Lee, 2010, used under CC BY-NC-ND 3.0 licence]
The views of the writer are not necessarily the views of the Daily Friend or the IRR.
If you like what you have just read, support the Daily Friend